 SHS296M GONE? NDA Spokesman Abiaz Rwamwiri, Faces Court Over Fake Accountabilities.
 H.E MUSEVENI AND H.E SAMIA SEAL THE OIL DEAL: EACOP 93.9% DONE, SGR NEXT
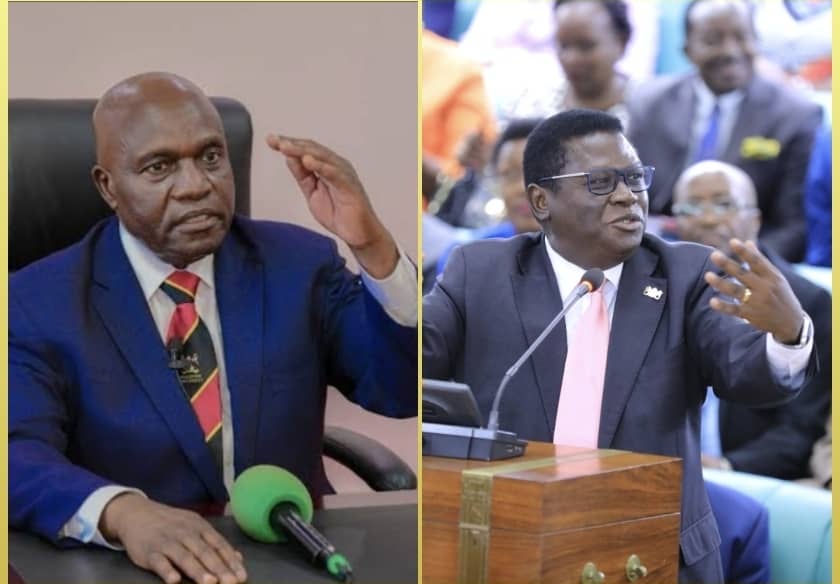 MAO TO MWENDA: You Cannot Beat People In Basements And Call It Transformation. Dr. KIYONGA Backs Him In Parliament.
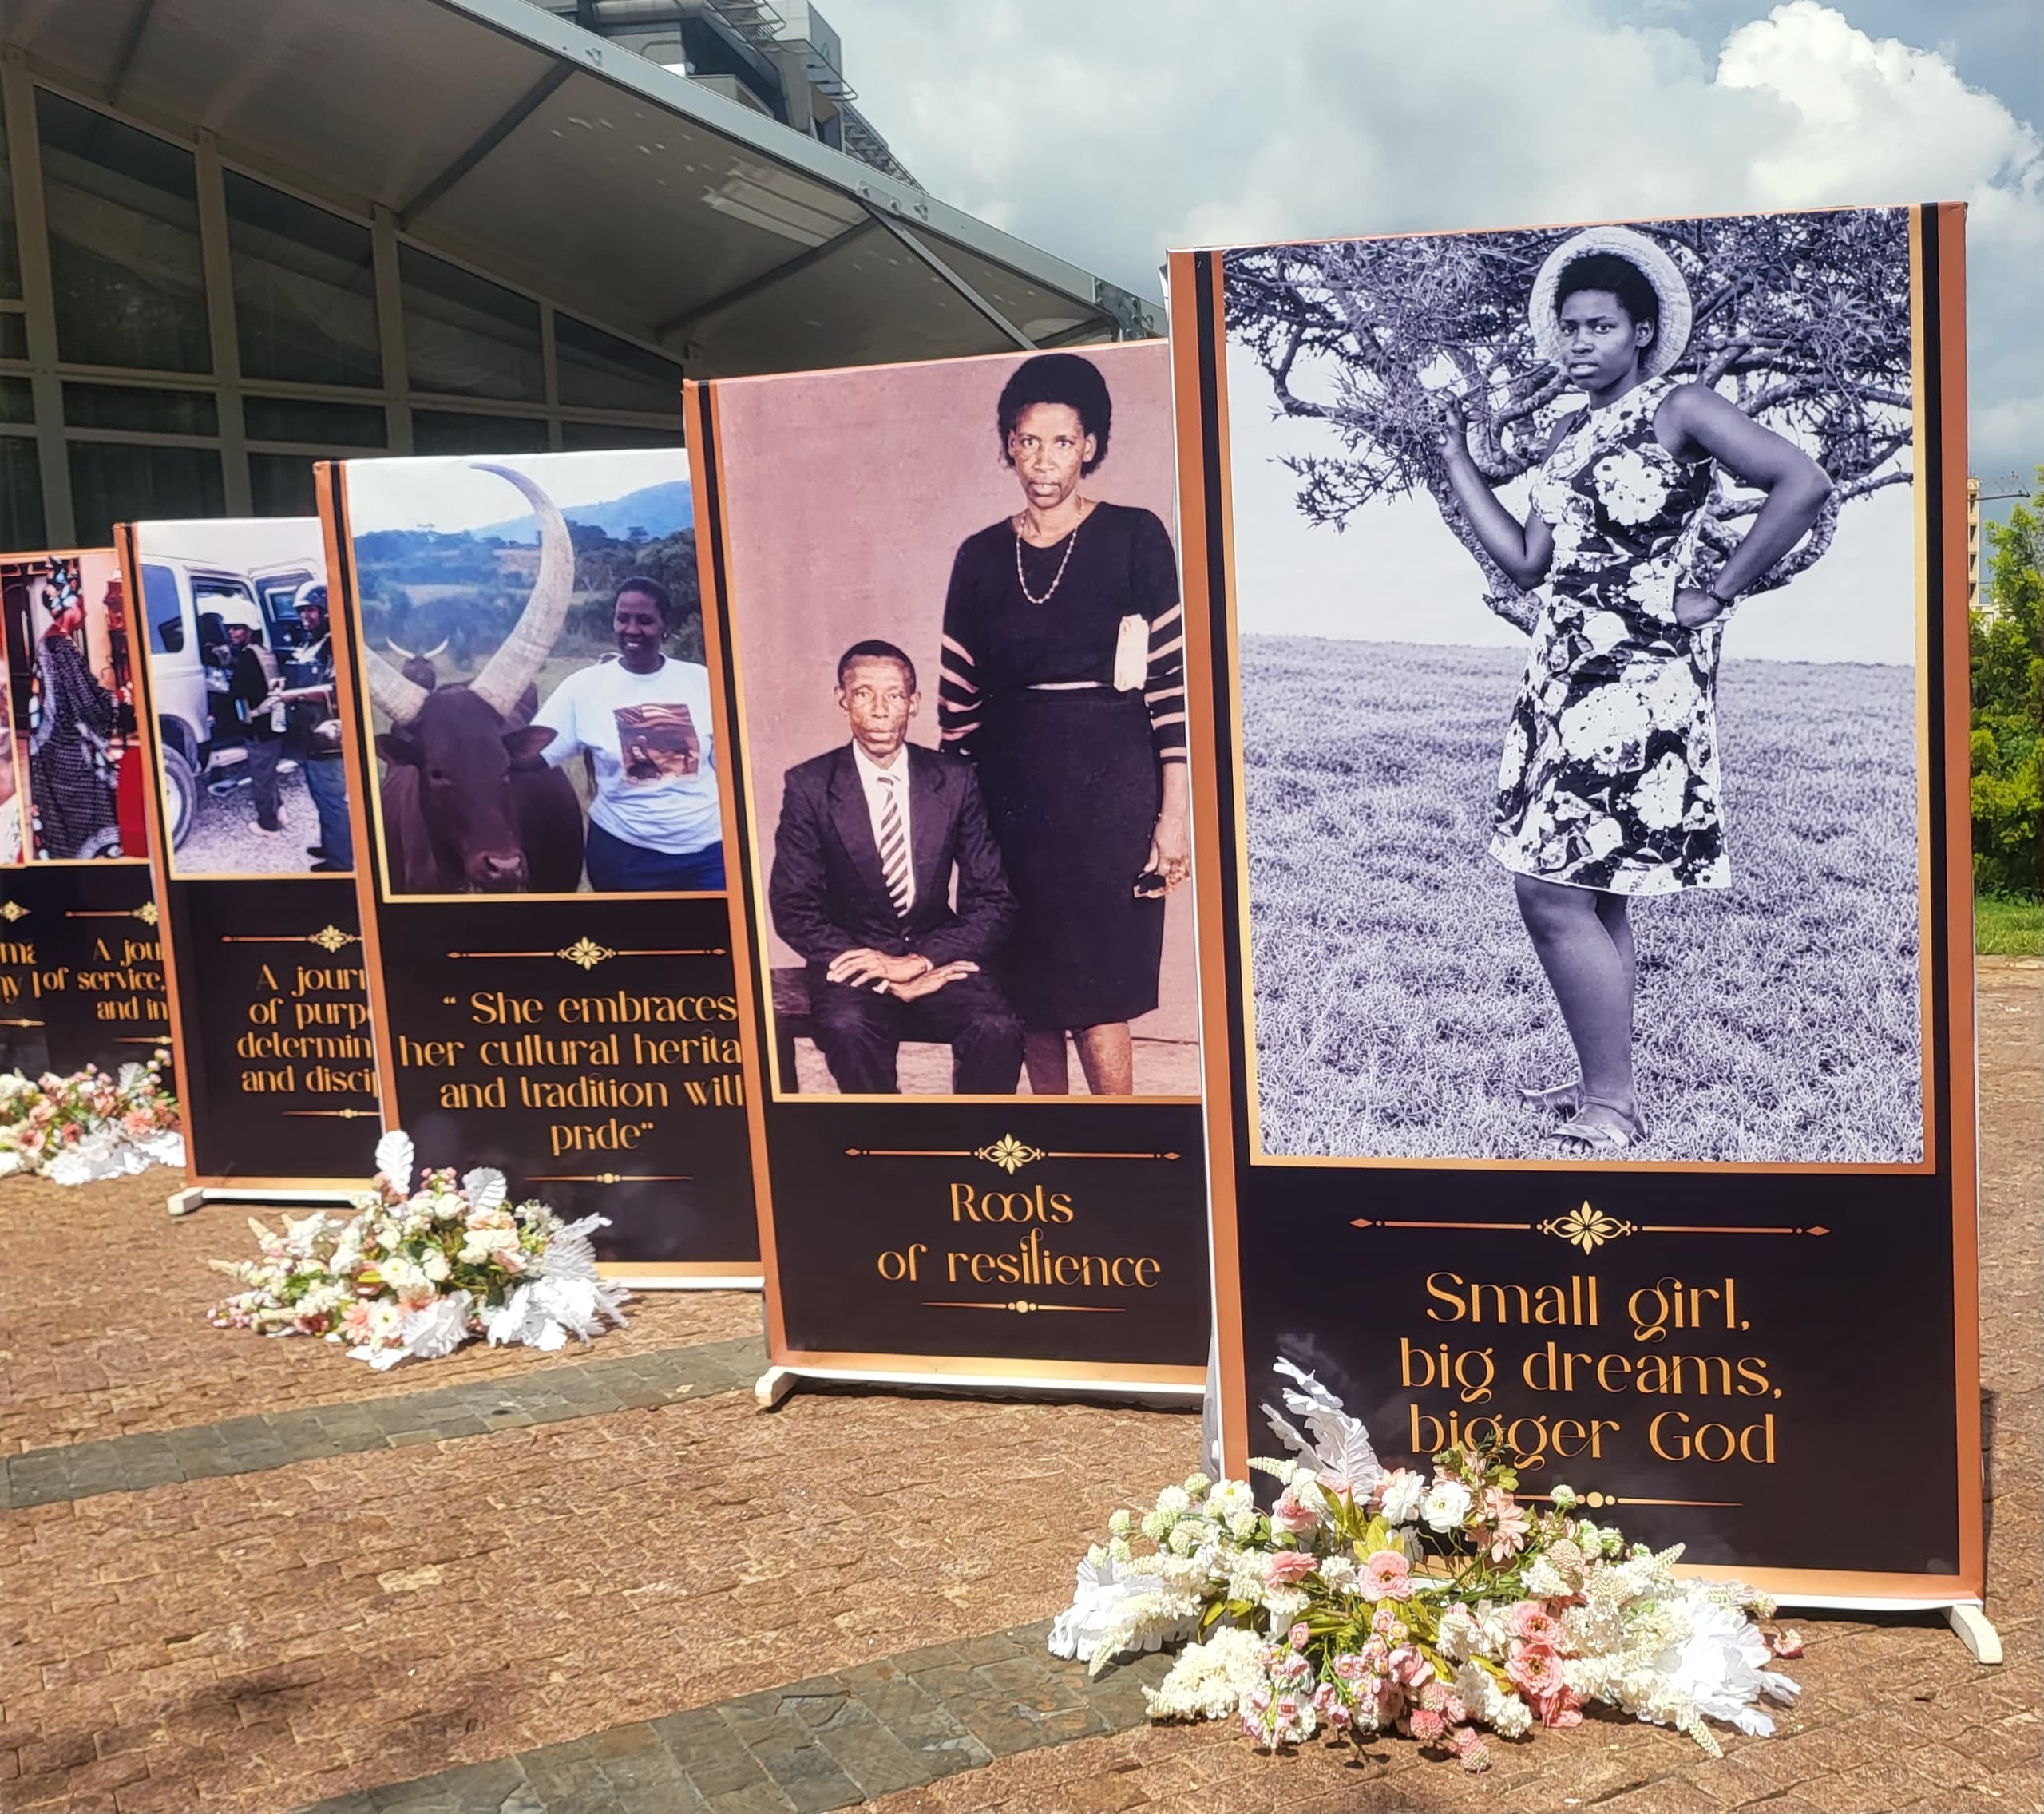 Dr. KELLEN KAYONGA: The Woman Who Needs No Title To Lead- Honoured At Glamorous Serena Dinner.
 10 YEARS IN JAIL FOR RIGGING ELECTIONS: Who Will Punish The Powerful? Tshisekedi’s New Referendum Law Explained.
URA Cannot Treat Every Bank Deposit as Business Income, Tribunal Rules
By Peter Luzinda
The Tax Appeals Tribunal has cautioned the Uganda Revenue Authority (URA) against automatically treating money deposited into company bank accounts as taxable business income, emphasising the need to establish the actual nature of financial transactions before raising tax assessments.
The position was highlighted in a dispute involving Salento General Enterprises Limited and URA, in which the company challenged assessments arising from the classification of bank deposits and accounting entries.
In a decision delivered on May 29, 2026, the Tribunal found that the disputed funds represented capital and operational financing rather than proceeds from taxable sales.
The Tribunal consequently set aside the assessments after determining that the amounts had been wrongly classified as business revenue.
The case, registered as Application No. 180 of 2024, centred on the treatment of money passing through the company's bank accounts and whether those deposits accurately represented income generated from its commercial activities.
Salento challenged URA's interpretation of the transactions, relying on corrected financial statements and supporting documentation to explain the source and purpose of the funds.
The Tribunal's decision highlights the distinction between a bank deposit and taxable income, noting that businesses may receive money through loans, shareholder contributions, capital injections and other financing arrangements that do not necessarily constitute sales.
However, the ruling does not give businesses automatic protection against tax assessments arising from unexplained deposits. Companies must still provide credible documentation to establish the nature of disputed transactions.
The decision also draws attention to Section 28 of the Tax Procedures Code Act, which places the burden of proving that a tax assessment is incorrect on the taxpayer.
For businesses, the ruling reinforces the importance of maintaining proper accounting records, bank statements, loan agreements and financial documentation to demonstrate how money received through their accounts should be treated for tax purposes.
It also provides guidance to URA on the importance of examining the underlying transactions rather than relying solely on bank deposit figures when determining taxable business income.
Leave a Comment
Your email address will not be published. Required fields are marked *